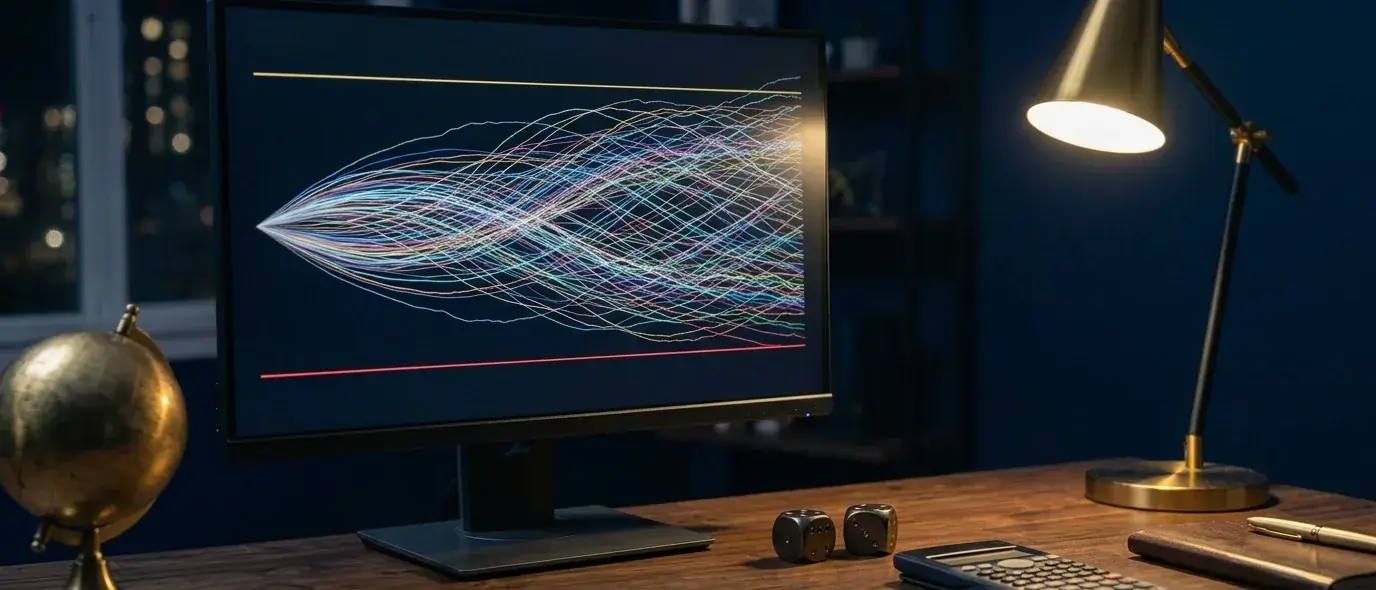
- An evaluation is a race between two barriers: the profit target and the drawdown floor. Your edge decides who wins far more than your entries do.
- With a 1:1.5 reward-to-risk, you need to win more than 40% of trades just to break even. Below that, no position size saves you.
- Once you have a real edge, smaller risk per trade raises your pass rate but stretches the time it takes, which costs money at monthly-billing firms.
- The real price of a funded account is fee ÷ pass probability + activation, not the sticker price.
Topstep reports that 16.8% of its Trading Combines were passed in 2025. That number isn’t a verdict on trader skill as much as on trader maths. Most failed evaluations were mathematically likely to fail on the day they were bought, because the trader’s risk per trade, win rate and reward-to-risk could not beat the barrier structure the firm sets up.
This guide works through that structure with simulations, so you can see what actually moves your odds and price the attempt before you pay for it.
An evaluation is a race between two barriers
A standard $50K futures evaluation gives you two lines. Reach $53,000 and you pass. Fall to the drawdown floor, $2,000 below your high point, and you fail. Every trade moves your balance up or down a step, and the account ends the moment it touches either line.
Mathematicians call this a gambler’s ruin problem, and it has three properties traders routinely underestimate:
- The target is further away than the floor. $3,000 up against $2,000 down means you need 1.5 times more favourable movement than unfavourable. On a forex two-step, phase one alone often asks for 8–10% against a 10% maximum loss, and then you do it again.
- A trailing floor moves toward you. Every new high drags the floor up behind it, so the room you have shrinks exactly when you start winning. Our drawdown guide covers the three types.
- Variance is not your friend unless your edge is real. A positive expectancy grinds you toward the target over many trades. Zero or negative expectancy means each extra trade is another chance for the floor to catch you.
Step one: do you have an edge at all?
Expectancy per trade, measured in units of risk (R), is:
Set it to zero and you get the break-even win rate for any reward-to-risk ratio:
| Reward : risk | Break-even win rate | What that means |
|---|---|---|
| 1 : 1 | 50.0% | Scalpers taking equal stops and targets need to win more than half |
| 1 : 1.5 | 40.0% | The most common intraday setup |
| 1 : 2 | 33.3% | Fewer winners needed, but each needs room to run |
| 1 : 3 | 25.0% | Trend trades; long losing streaks are normal |
Commissions and slippage come straight off the reward side. On a $200 risk with a 30-point NQ micro stop, a few dollars of round-turn cost per contract can shave several percentage points off a thin edge. Measure your win rate and average reward from at least 50–100 trades of real (or sim) history at the size you plan to use. Ten good trades is not a sample.
What the simulations show
We simulated 20,000 evaluations for each combination below: a $50K account, $3,000 target, $2,000 trailing drawdown that locks at the starting balance, and a fixed $200 risk per trade (one-tenth of the drawdown). Each cell shows the pass rate and, after the slash, the average number of trades it took to pass.
| Reward : risk | 35% wins | 40% wins | 45% wins | 50% wins | 55% wins |
|---|---|---|---|---|---|
| 1 : 1 | 0% | 0% | 3% / 99 | 26% / 113 | 68% / 96 |
| 1 : 1.5 | 5% / 69 | 26% / 78 | 63% / 69 | 88% / 53 | 97% / 40 |
| 1 : 2 | 37% / 56 | 69% / 48 | 89% / 38 | 97% / 30 | 99% / 23 |
The same grid with a static floor (it never moves up) shows how much the trailing drawdown costs you:
| Reward : risk | 35% wins | 40% wins | 45% wins | 50% wins | 55% wins |
|---|---|---|---|---|---|
| 1 : 1 | 0% | 0% | 4% | 38% | 87% |
| 1 : 1.5 | 6% | 39% | 82% | 97% | 99% |
| 1 : 2 | 55% | 87% | 97% | 99% | 100% |
Three things stand out:
- At break-even, you will most likely fail. A 40% win rate at 1:1.5 has zero expectancy, yet passes only 26% of the time with a trailing floor. The target is 1.5 times further than the floor, so a random walk hits the floor first.
- A small edge changes everything. Moving from 40% to 45% wins at 1:1.5 lifts the pass rate from 26% to 63%. That 5-point improvement in win rate is worth more than any choice of firm.
- Trailing drawdown costs roughly 10–20 percentage points of pass rate in the middle of the grid. If your strategy is marginal, a static or end-of-day floor is worth paying for.
The position-size paradox
Traders often size up to “pass faster”. Whether that helps depends entirely on your edge. Here is the 1:1.5 setup at two win rates, with only the risk per trade changing:
| Risk per trade | 40% wins (no edge) | 45% wins (real edge) |
|---|---|---|
| $100 (5% of drawdown) | 19%, ~230 trades | 82%, ~190 trades |
| $200 (10%) | 26%, ~78 trades | 63%, ~69 trades |
| $300 (15%) | 28%, ~36 trades | 55%, ~34 trades |
| $500 (25%) | 27%, ~14 trades | 44%, ~13 trades |
| $1,000 (50%) | 29%, ~3 trades | 37%, ~4 trades |
With a real edge, small size lets the edge play out: pass rate climbs to 82% at $100 per trade. Without an edge, size barely matters, because you are flipping a weighted coin either way. Big size just finishes the coin-flipping sooner.
The real cost of a funded account
If your pass probability is p, the average number of attempts you will buy is 1 ÷ p. So the expected cost of getting funded is:
For monthly-billing firms, “fee per attempt” is the monthly price times the months an attempt lasts. That turns slow, careful trading (which raises p) into a real cost, and is why the cheapest sticker price is often not the cheapest route. A worked example for a trader with a 45% win rate at 1:1.5, risking $200 a trade (63% pass rate, about 69 trades, so roughly two months at two trades a day):
| Account | Fee per attempt | ÷ pass rate | + activation | Expected cost |
|---|---|---|---|---|
| $49/month, $149 activation | $98 (2 months) | $156 | $149 | $305 |
| $160 one-time, no activation | $160 | $254 | $0 | $254 |
| $1190 one-time, with coupon ($119), no activation fee | $119 | $189 | $0 | $189 |
The ranking flips depending on how long you take and how often you pass. Run your own numbers below, then compare firms on the cheapest futures firms list and check current sales on the deals page.
Run your own simulation
Enter your real statistics. The simulator runs 5,000 evaluations in your browser with the drawdown type you choose and gives your pass probability, typical time to pass and expected cost.
Expectancy 0.13R per trade. Check the result against a lower win rate too: your real one could be a few points worse.
What the model leaves out
- Trades aren’t independent. Real losing streaks cluster around regime changes and tilt. Treat the simulated pass rate as a ceiling, not a promise.
- End-of-day vs intraday trailing. The simulator trails on closed trades. Intraday trailing (Bulenox, TradeDay) also trails open profit, so give back more of each winner and the real pass rate drops further.
- Daily loss limits and consistency rules add extra ways to fail or delay a pass. See consistency rules decoded.
- Your statistics are estimates. A 45% win rate measured over 40 trades could easily be 38% or 52%. Run the simulator at the low end of your range.